Mauri Hawkins, Chief Claims Counsel, Alliant National
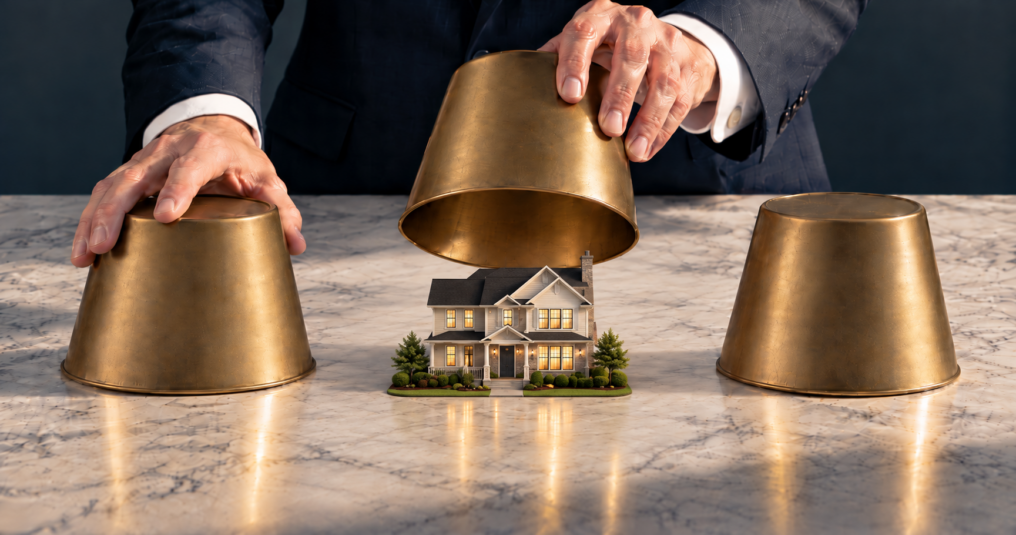
For some who have been in the title industry for many years, the foreclosure rescue scheme is not new. Nevertheless, fraudsters sadly are recycling this scheme under the guise that they are helping a homeowner in a time of desperate need.
Freddie Mac states a “foreclosure rescue scheme is a type of fraud that takes advantage of homeowners who have fallen behind on their mortgage payments. The fraud perpetrator approaches the homeowner with promises of paying off the delinquent mortgage and helping the homeowner stay in the property.”
Looking at the first half of 2026, CBS News reported that the country has seen a 21% increase in 2026 foreclosures when compared with 2025, and it is 28% higher when compared with 2024 foreclosures.
Fraudsters can be someone who is known to the homeowner, or the fraudster can be a stranger that may contact the homeowner with promises that they will “save their home.” The federal government and several state and local governments have provided information to warn and assist consumers about foreclosure rescue scams.
Fraudsters typically utilize psychological tactics and legal-sounding jargon to make matters seem legitimate to a homeowner. Here are a few common ways the fraudster may operate:
- Money upfront: The fraudster may charge a significant upfront fee, promising to negotiate a loan modification with the homeowner’s lender. Once the consumer pays, the fraudster disappears (no longer able to reach the fraudster at the same number or email previously used to communicate), or the fraudster drags out the process until it is too late to save the consumer’s home as the underlying foreclosure continues to move forward.
- Rent-to-Own option: The fraudster may convince the homeowner to surrender the deed, but only temporarily, and claim that it can rent the home back to the homeowner while they get themselves back into a better financial position. Once the homeowner agrees, the fraudster may start the eviction process and seek to obtain possession of the home.
- Bait-and-Switch: The homeowner believes they are signing a new mortgage but included in the stack of documents is a deed to transfer title to the fraudster or a related entity. Now the home is in possession of the fraudster to do what the fraudster wants with the property. In some cases, once the fraudster has stripped all of the property’s equity, they may even deed the property back to the homeowner, who will now be named in future foreclosure lawsuits. In other cases, the fraudster may sell the property to a new and unsuspecting buyer.
Each of the above-mentioned versions of the scheme relies on the homeowner’s desire and determination to not lose their home. In these cases, homeowners who fall victim to these schemes most likely are not covered under an owner’s title insurance policy due to the homeowner’s affirmative actions taken after the policy date. However, in cases where a subsequent bona fide purchaser or lender acquires an interest in the property, these pre-policy actions may result in those parties filing a notice of title insurance claim with their title insurer. This may warrant coverage under the bona fide purchaser’s or lender’s specific policy which may result in expenses and losses for a title insurer.
In conclusion, if a homeowner falls behind in paying their mortgage loan, it is recommended that the homeowner speak with their lender or loan servicer to discuss possible options that may be available to the homeowner instead of becoming a victim of a fraudster’s foreclosure rescue scam. Also, as a consumer, do not hesitate to contact your state’s consumer protection division or fraud protection division to report the foreclosure rescue scheme. Such action can protect others in the community.
References:
American Land Title Association, ALTA Owner’s Policy of Title Insurance (2021), Exclusions From Coverage, paragraph 3.a. created, suffered, assumed, or agreed to by the Insured Claimant and 3.d. attaching or created subsequent to the Date of Policy, https://www.alta.org/news-and-publications/news/20250819-ALTA-Releases-Endorsements-to-Protect-Against-Forgery-Seller-Impersonation-Fraud.
American Land Title Association, August 19, 2025, ALTA Releases Endorsements to Protect Against Forgery, Seller Impersonation Fraud, https://www.alta.org/news-and-publications/news/20250819-ALTA-Releases-Endorsements-to-Protect-Against-Forgery-Seller-Impersonation-Fraud.
CBS News, July 16, 2026, Foreclosure filings surged 21% this year. Here are the states where they are rising fastest, https://www.cbsnews.com/news/us-foreclosures-homeowners-financial-strain-attom/
Federal Deposit Insurance Corporation, Beware of Foreclosure Rescue Scams, https://www.fdic.gov/consumers/loans/prevention/rescue/images/foreclosurescam.pdf
Freddie Mac, Foreclosure Rescue Scheme, https://sf.freddiemac.com/working-with-us/fraud-prevention/emerging-fraud-trends/foreclosure-rescue-scheme
News 4 Jax, Florida posts nation’s worst foreclosure rate in first half of 2026; Jacksonville among worst-hit metros, ATTOM says, https://www.news4jax.com/news/local/2026/07/17/florida-posts-nations-worst-foreclosure-rate-in-first-half-of-2026-jacksonville-among-worsthit-metros-attom-says/
U.S. Department of the Treasury, Beware of Foreclosure Scams, https://home.treasury.gov/data/troubled-assets-relief-program/housing/beware-of-scams
Westchester County, Foreclosure Rescue Scams, https://consumer.westchestercountyny.gov/index.php?option=com_content&view=article&id=2609:foreclosure-rescue-scams&catid=207:alerts-and-scams
This blog contains general information only, not intended to be relied upon as, nor a substitute for, specific professional advice. We accept no responsibility for loss occasioned to any purpose acting on or refraining from action as a result of any material on this blog.